










Sanghvi Movers expects project EPC EBITDA reversal in Q2-Q3
Key highlights
- Sanghvi Movers expects project EPC revenue recognition to be completed in Q2 and Q3 of this year.
- Management expects the project EPC wind-up to reverse negative operational EBITDA within standalone results.
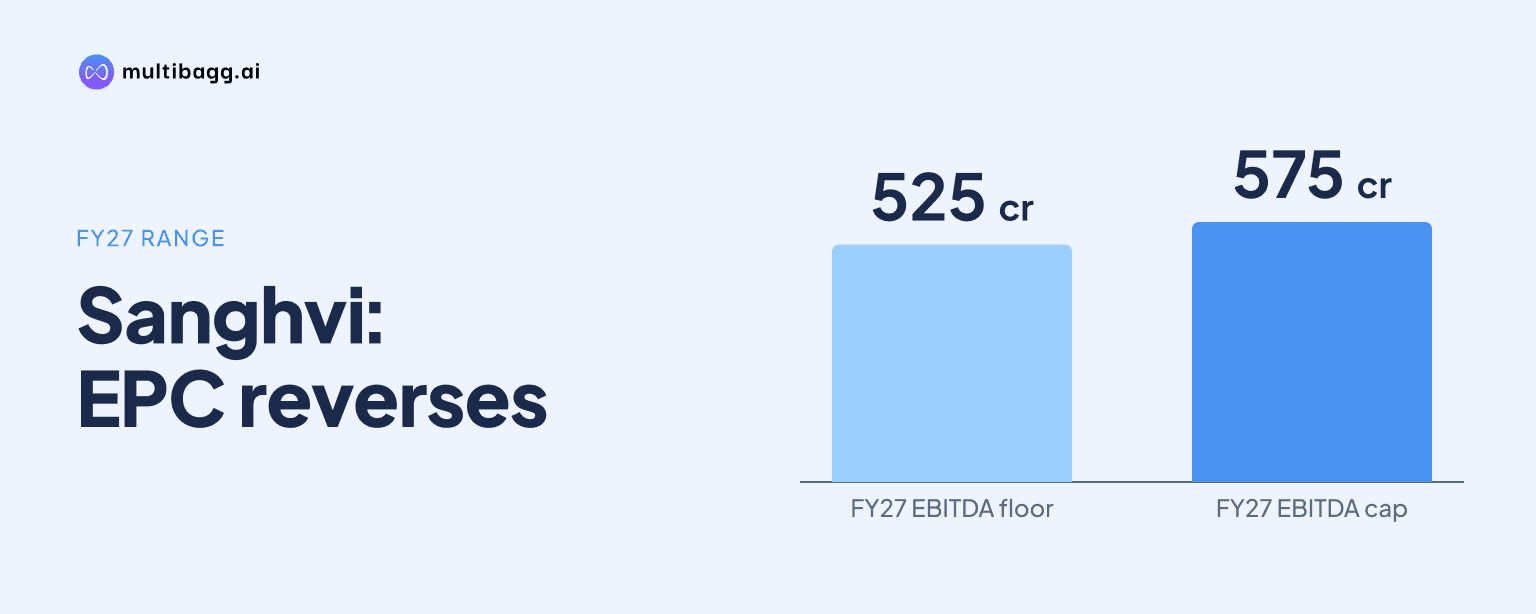
- Sanghvi Movers reaffirmed FY27 EBITDA guidance of Rs 525 crore to Rs 575 crore.
- FY27 capital expenditure is planned at Rs 583 crore, with roughly Rs 400 crore remaining after H1.
powered by IRIS
Sanghvi Movers Limited expects negative operational EBITDA, or earnings before interest, tax, depreciation and amortisation, from its project EPC vertical to reverse after revenue recognition is completed in Q2 and Q3 of this year. Management said the vertical, which is included in standalone results, is being wound up rather than expanded.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
Why is Sanghvi Movers winding up project EPC?
Sanghvi Movers is winding up project EPC and expects to finish the vertical’s remaining revenue recognition in Q2 and Q3 of this year. Responding to an investor’s question, Rishi Sanghvi said completing that recognition should reverse the negative operational EBITDA shown on page 31 of the company presentation.
The disclosure describes an exit from the vertical, not a turnaround plan. Management did not disclose the amount of negative operational EBITDA, project EPC revenue, the number or value of remaining contracts, closure costs, or a final legal closure date. The defined milestone is completion of revenue recognition during the second and third quarters.
Project EPC is not reported as a separate business segment. Management said it falls under Sanghvi Movers’ standalone results, meaning its revenue, expenses and EBITDA cannot be isolated from a separately disclosed segment statement on the basis of this call. The reported negative operational EBITDA is therefore part of standalone performance rather than an identified consolidated line item.
How could the project EPC exit affect Sanghvi Movers’ EBITDA?
Sanghvi Movers expects the wind-up to reverse negative operational EBITDA, but management did not quantify the expected improvement in rupees. The expected reversal remains a management expectation dependent on completing the remaining Q2 and Q3 revenue recognition, rather than an improvement already reported in financial results.
The effect matters because project EPC is within standalone results. If revenue recognition is completed as management described, the same negative operating contribution should no longer remain in the standalone business mix. However, the call did not disclose whether receivable collections, contract settlements, provisions or further write-offs could arise during the closure, so the final financial effect cannot be calculated from the available information.
Management separately reaffirmed full-year EBITDA guidance of Rs 525 crore to Rs 575 crore. Rishi Sanghvi said that guidance remained intact “because of H1,” rather than despite first-half performance. The company did not provide a numerical bridge between the project EPC negative EBITDA and the full-year EBITDA range, so the guidance is not a stand-alone forecast for the exit.
The core operating indicators discussed on the call were mainly linked to crane activity rather than project EPC. Sanghvi Movers reported utilization of 86% in the first quarter and 78% in the first half, with the first-half figure reflecting a monsoon-related slowdown. No equivalent utilization, margin or order-book measure was disclosed for the project EPC vertical.
Got a follow-up? Ask IRIS
Is project EPC the same as Sanghvi Movers’ wind E&C business?
No. Sanghvi Movers identified project EPC as the standalone-results vertical being wound up, while it discussed wind engineering and construction, or E&C, as an operating activity where it is pursuing wider work scopes. The call does not support interpreting the project EPC exit as a withdrawal from wind E&C.
In wind E&C, management said contracts are fixed-price and do not allow cost escalations to be passed on to customers. It described services for independent power producers that include land permits and approvals, mechanical work such as crane deployment, inter-carting and installation, electrical work including USS, SCADA and 33-kilovolt lines, plus engineering, design and civil works.
Management attributed wind E&C revenue growth to larger composite contracts and Sanghvi Movers’ delivery record. It said the parent company has erected more than 20 gigawatts of India’s 55 gigawatts of wind-energy capacity. Management also cited framework discussions and memoranda of understanding with original equipment manufacturers that could establish Sanghvi Movers as an exclusive E&C partner.
The distinction affects how the exit should be read. Project EPC has negative operational EBITDA and is being closed, whereas wind E&C was presented as an area where Sanghvi Movers is securing broader project scopes. The call did not provide a reconciliation between the activities or establish whether they share contracts, staff, customers or equipment.
What should investors watch through the Q3 presentation?
Investors should watch whether Sanghvi Movers confirms completion of project EPC revenue recognition within the Q2-Q3 schedule and reports the expected reversal of negative operational EBITDA. Management said it would next meet investors for its Q3 presentation, making that event the stated opportunity for an update on the wind-up.
The FY27 capital expenditure plan is another execution measure for the second half. Management said total FY27 capital expenditure is Rs 583 crore, of which Rs 90 crore was capitalised in Q2, taking H1 capitalised expenditure to Rs 182 crore. That leaves roughly Rs 400 crore for the rest of the year, which management said typically falls in Q3 and Q4 after the monsoon as domestic crane offtake and project execution rise.
Debt servicing and funding plans will also be relevant alongside the closure. Management projected FY27 debt-to-equity of around 0.7 to 0.75 and said Rs 120 crore of term-loan payments remained due in H2. In response to a question about a rights issue or subsidiary listing, Rishi Sanghvi said the company was not looking to raise equity at that point.
Saudi Arabia remains a separate operating variable. Sanghvi Movers reported 86% utilization, a 3.8% yield and days sales outstanding of 165 in the region in H1, compared with 201 days previously. Management said logistics constraints and the availability of manpower and materials had delayed projects by one to two quarters, while describing Middle East exposure as less than 5% of the business.
Conclusion
Sanghvi Movers has set out a specific mechanism for removing a negative contribution from its standalone results: wind up project EPC and complete its residual revenue recognition in Q2 and Q3. Management expects that process to reverse negative operational EBITDA, while continuing to discuss wind E&C and crane operations as separate areas of activity.
The next disclosed checkpoint is the Q3 presentation, when management may confirm whether the Q2-Q3 revenue-recognition timetable was met and whether the EBITDA reversal occurred. Investors can also track progress on roughly Rs 400 crore of remaining FY27 capital expenditure, the projected 0.7 to 0.75 debt-to-equity level and Rs 120 crore of H2 term-loan payments.