










Sanghvi Movers sees up to Rs 160 crore order spillover in FY27
Key highlights
- Sanghvi Movers said Rs 140 crore to Rs 160 crore of its Rs 1,582 crore order book may spill into the next year.
- The Rs 1,582 crore order book at October 23, 2026 was 26% above Rs 1,253 crore at July 24, 2026.
- Renewable E&C accounted for Rs 854 crore of the order book, versus Rs 683 crore in India and Botswana crane rental.
- Sanghvi Movers reaffirmed FY27 total-income guidance of Rs 1,400 crore to Rs 1,500 crore.
powered by IRIS
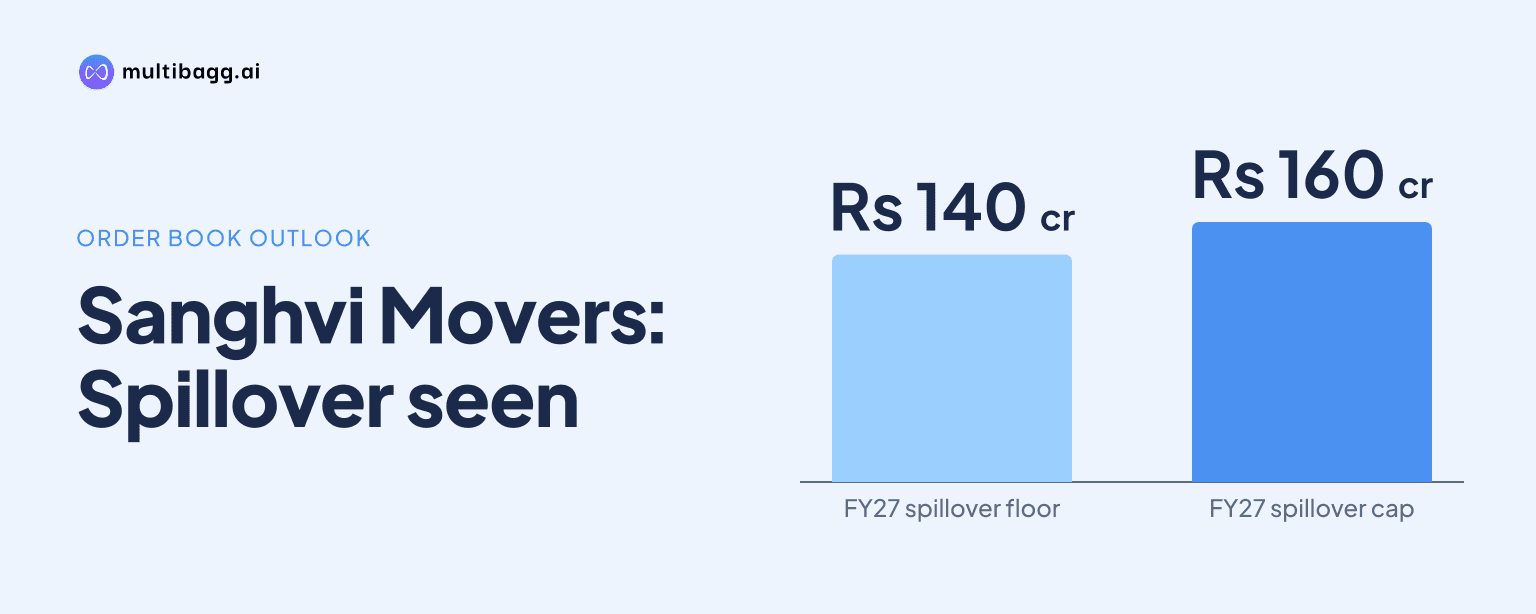
Sanghvi Movers said during financial year 2027 (FY27) that up to Rs 160 crore, or 10%, of its Rs 1,582 crore order book at October 23, 2026 could spill into the next financial year, principally because renewable Engineering and Construction project execution can be delayed.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
How much of Sanghvi Movers' order book could spill into next year?
Sanghvi Movers estimates that 8% to 10% of its Rs 1,582 crore order book could move into the next year, equal to Rs 140 crore to Rs 160 crore. Rishi Sanghvi gave the range while explaining why management retained FY27 total-income guidance of Rs 1,400 crore to Rs 1,500 crore despite the 26% increase in the order book in 13 weeks.
The estimate applies principally to the Engineering and Construction (E&C) business, rather than to all contracted work. Pradeep Mehta said the October 23 order book was executable in FY27, but E&C projects have an ongoing 10% possibility of deferral, including from right-of-way issues. Management later quantified that risk at Rs 140 crore to Rs 160 crore.
Sanghvi Movers' renewable E&C business generated Rs 365 crore of total income in the first half (H1) of FY27, with an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of about 14%. Management said execution timing and percentage-of-completion accounting can produce quarter-to-quarter changes in reported revenue, making project delivery central to the timing of that segment's income.
What is in Sanghvi Movers' Rs 1,582 crore order book?
Sanghvi Movers' Rs 1,582 crore group order book included Rs 854 crore in renewable E&C, Rs 683 crore in India and Botswana crane rental, and Rs 45 crore in Gulf Cooperation Council (GCC) crane rental. The total was 26% above Rs 1,253 crore reported on July 24, 2026.
Renewable E&C was the largest disclosed part of the book at Rs 854 crore, exceeding the Rs 683 crore in India and Botswana crane rental. That composition explains why E&C-specific constraints could affect group revenue timing, even though management described the order book as intended for execution during FY27.
Management also reported an enquiry pipeline of about Rs 6,700 crore across segments. Sanghvi Movers did not state what share of that pipeline could convert into FY27 revenue, distinguishing the Rs 6,700 crore potential funnel from the Rs 1,582 crore booked work already reported on October 23.
Got a follow-up? Ask IRIS
Why could Sanghvi Movers' renewable projects be delayed?
Sanghvi Movers cited grid connectivity, power purchase agreement (PPA) offtake, site availability and wind turbine generator supply from original equipment manufacturers as factors that can delay E&C execution. Management also referred to monsoon disruption extending into the third quarter and possible internal challenges in delivering projects to customer schedules.
These dependencies can postpone project delivery and revenue recognition on the Rs 854 crore renewable E&C order book. Sanghvi Movers also said its E&C contracts are fixed-price, with no pass-through of cost escalation to customers, meaning timing and execution remain relevant to contract delivery as well as reported revenue.
Monsoon conditions had already affected crane-rental activity in the second quarter. India utilisation declined to 71% in the second quarter of FY27 from 86% in the first quarter, although it was above 70% a year earlier, while yield increased to 2.20% from 2.04%. Management described the decline as a normal seasonal slowdown and expects deployment to improve as project activity normalises.
Collections showed a separate improvement in H1 FY27. Group days sales outstanding, or DSO, fell to 81 days from 116 days in the first quarter, while renewable E&C DSO was below 60 days, compared with 89 days for India and Botswana crane rental and 165 days for GCC. Management presented those figures as working-capital progress, not as a resolution of execution dependencies.
Does Sanghvi Movers still stand by its FY27 guidance?
Sanghvi Movers reaffirmed FY27 total-income guidance of Rs 1,400 crore to Rs 1,500 crore and EBITDA guidance of Rs 525 crore to Rs 575 crore. Management said a Rs 140 crore to Rs 160 crore spillover from the existing Rs 1,582 crore order book could place revenue within the stated total-income range.
The guidance follows H1 FY27 revenue from operations of Rs 656 crore, up 36% year on year. EBITDA rose 25% and profit after tax increased 22%, while second-quarter revenue grew 32% and EBITDA margin was 20%. Rishi Sanghvi said the EBITDA guidance remained intact because of the first-half performance.
India and Botswana crane rental reported H1 total income of Rs 406 crore, utilisation of 78%, yield of 2.24% and EBITDA margin of 46%. GCC crane rental reported Rs 39 crore of H1 total income, 86% utilisation, 3.80% yield and a positive EBITDA margin of 24%, compared with the renewable E&C business's Rs 365 crore H1 income and approximately 14% margin.
GCC expansion faces a different timing issue from Indian renewable projects. Sanghvi Movers said shipping disruption, vessel-availability constraints and port congestion delayed crane deliveries in Saudi Arabia, causing Rs 80 crore to Rs 90 crore of capital expenditure to be deferred to FY28. Management said GCC projects were delayed by one to two quarters because of logistics and site availability of manpower and materials, although H1 utilisation remained 86%.
Conclusion
Sanghvi Movers has put a numerical range around the execution risk in its FY27 order book: Rs 140 crore to Rs 160 crore of the Rs 1,582 crore total may shift into the following year. The exposure is most relevant to renewable E&C, which represented Rs 854 crore of booked work and faces dependencies including grid connection, PPA offtake, turbine supply and site readiness.
The next disclosures to watch are second-half execution and the delivery of Rs 401 crore of remaining FY27 capital expenditure after Rs 182 crore was capitalised in H1. Management has also deferred Rs 80 crore to Rs 90 crore of Saudi capital expenditure to FY28, pending an improvement in shipping costs, vessel availability and port conditions.