










Life Insurance Corporation of India Q2 Profit Rises 20%
Key highlights
- LIC reported Q2 FY27 consolidated net profit of ₹12,114.78 crore, up 19.97% year-on-year.
- Net premium income increased 16.2% to ₹1,47,433.15 crore in Q2 FY27.
- VNB rose 61% to ₹3,136 crore and the VNB margin expanded to 22.9% from 15.4%.
- LIC's GNPA ratio declined to 1.16% from 1.21% in the preceding quarter.
powered by IRIS
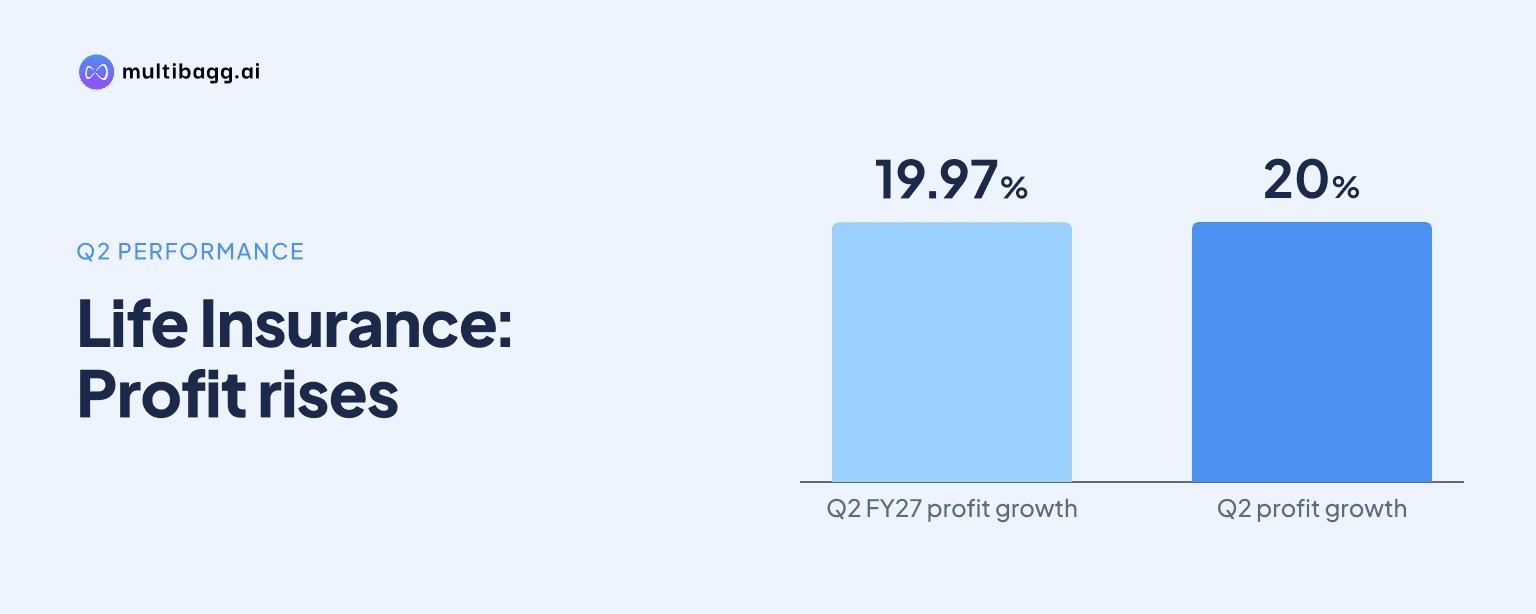
Life Insurance Corporation of India reported consolidated net profit of ₹12,114.78 crore for Q2 FY27, a 20.0% year-on-year increase, supported by 16.2% growth in net premium income to ₹1,47,433.15 crore. The July-September performance also included a sharp improvement in new-business profitability and a lower gross non-performing asset ratio.
Know Life Insurance Corporation of India inside out
Results, valuation, peers and who's buying, in one view.
What did Life Insurance Corporation of India report for Q2 FY27?
Life Insurance Corporation of India reported its reviewed consolidated results for the quarter ended September 30, 2026, on November 5, 2026. Consolidated net profit rose to ₹12,114.78 crore from ₹10,098.48 crore in Q2 FY26, representing growth of 19.97% year-on-year. The result was driven by higher premium collections across the insurer's business.
Net premium income increased to ₹1,47,433.15 crore from ₹1,26,930.04 crore a year earlier. Total consolidated income rose 9.7% to ₹2,64,861 crore from ₹2,41,536 crore. Net investment income increased nearly 2.5% to about ₹1,15,000 crore during the quarter, adding to the insurer's overall income performance.
The reported quarterly profit was lower than the ₹13,584.25 crore recorded in the preceding quarter. The year-on-year comparison, however, showed profit growth alongside higher net premium income. LIC's results are important because the state-owned insurer remains a major participant in India's life insurance market and manages a large policyholder base.
Which premium segments supported LIC's first-half performance?
LIC's premium growth in the first half of FY27 was led by group business, while individual business also expanded. Total premium income for H1 FY27 increased 11.6% to ₹2,74,269 crore. Individual new-business premium income rose 14.9% to ₹32,725 crore, and individual renewal premium income increased 4.7% to ₹1,27,950 crore.
Total individual business premium income grew 6.6% to ₹1,60,675 crore during the six months ended September 2026. Group business premium income rose 19.6% to ₹1,13,594 crore, including a 20.6% rise in group new-business premium income to ₹1,11,685 crore. These figures show that group business made a larger contribution to premium growth than individual business over the half year.
LIC sold about 71 lakh individual policies in H1 FY27, compared with 72.6 lakh policies in the corresponding period a year earlier. While the policy count declined 2.3%, premium income from individual business increased. The results also showed annualised premium equivalent, or APE, rising 3.8% to ₹17,004 crore in Q2 FY27 from ₹16,382 crore in Q2 FY26.
For H1 FY27, APE increased 5.72% year-on-year to ₹30,696 crore. Individual APE rose 0.31% to ₹17,224 crore. The product mix changed during the quarter, with the share of non-participating products declining to 34.03% from 36.31% a year earlier, while participating products accounted for 65.98%.
Got a follow-up? Ask IRIS
How did LIC's new-business profitability and asset quality change?
LIC's Value of New Business rose 61% year-on-year to ₹3,136 crore in Q2 FY27, and its VNB margin expanded by 750 basis points to 22.9%. VNB measures the present value of expected future profits from new policies written during a period. The rise in both VNB and margin indicates a stronger reported profitability profile for new business than in Q2 FY26, when the margin was 15.4%.
The insurer's H1 FY27 net VNB increased 33.95% to ₹6,846 crore from ₹5,111 crore in the corresponding period of the previous financial year. LIC also said it launched five new non-participating individual products during the first six months of FY27. These product launches formed part of its business activity during the half year.
Asset quality improved sequentially, with the gross non-performing asset ratio declining to 1.16% from 1.21% in the preceding quarter. This was a quarter-on-quarter improvement of 5 basis points. The reported data does not provide a year-on-year comparison for the GNPA ratio in the supplied results.
Standalone operating data also showed management expenses declining slightly to ₹15,061.49 crore in Q2 FY27 from ₹15,234.37 crore a year earlier. Net commission increased to ₹6,055.76 crore from ₹5,772.15 crore. Benefits paid to policyholders rose to ₹1,34,186.08 crore from ₹1,06,250.36 crore, reflecting the scale of LIC's continuing policyholder obligations.
What do the results mean for policyholders and investors?
The Q2 FY27 results show that LIC generated higher premium income and reported improved new-business profitability, while its GNPA ratio moved lower from the prior quarter. For policyholders, the rise in benefits paid and the continuing expansion in premium income are operating figures within a large life insurance business. The results do not alter the terms or benefits of individual insurance policies.
For investors, the key reported measures are the 20.0% increase in consolidated profit, 16.2% growth in net premium income, and the 750-basis-point expansion in VNB margin. The sequential decline in profit from ₹13,584.25 crore in the prior quarter is also part of the reported comparison. No LIC share-price movement or market reaction was provided in the results information.
The results come as life insurers focus on premium growth, product mix and profitability of new policies. LIC's lower non-participating product share and higher participating product share were reported alongside the improvement in VNB margin. The available figures do not establish a direct cause-and-effect relationship between this mix change and the margin movement.
LIC also addressed the proposed sale of IDBI Bank to Fairfax Financial Holdings in relation to its bancassurance channel, stating that it expects the lender to continue as a distribution partner. This is relevant to LIC's distribution network, although the supplied information does not quantify the channel's premium contribution or provide a timeline for the proposed sale.
Conclusion
LIC's Q2 FY27 performance combined higher consolidated profit, stronger net premium income and a substantial rise in reported new-business value. The 20.0% increase in net profit to ₹12,114.78 crore and the increase in VNB margin to 22.9% were the main financial outcomes, while the GNPA ratio improved sequentially to 1.16%.
The next disclosed operating markers are the insurer's premium trends across individual and group business, the progress of its five newly launched non-participating individual products, and developments around IDBI Bank's proposed sale and LIC's expected continuation as its distribution partner.