










Redington Limited Q2 FY27 revenue rises 48% to ₹43,002 crore
Key highlights
- Redington Limited reported Q2 FY27 consolidated revenue of ₹43,002 crore, up 48% year on year.
- PAT excluding exceptional items rose 50% year on year to ₹581 crore in Q2 FY27.
- India revenue increased 67% year on year, while Technology Solutions Group revenue grew 91%.
- H1 FY27 revenue reached ₹77,967 crore and PAT excluding exceptional items reached ₹1,067 crore.
powered by IRIS
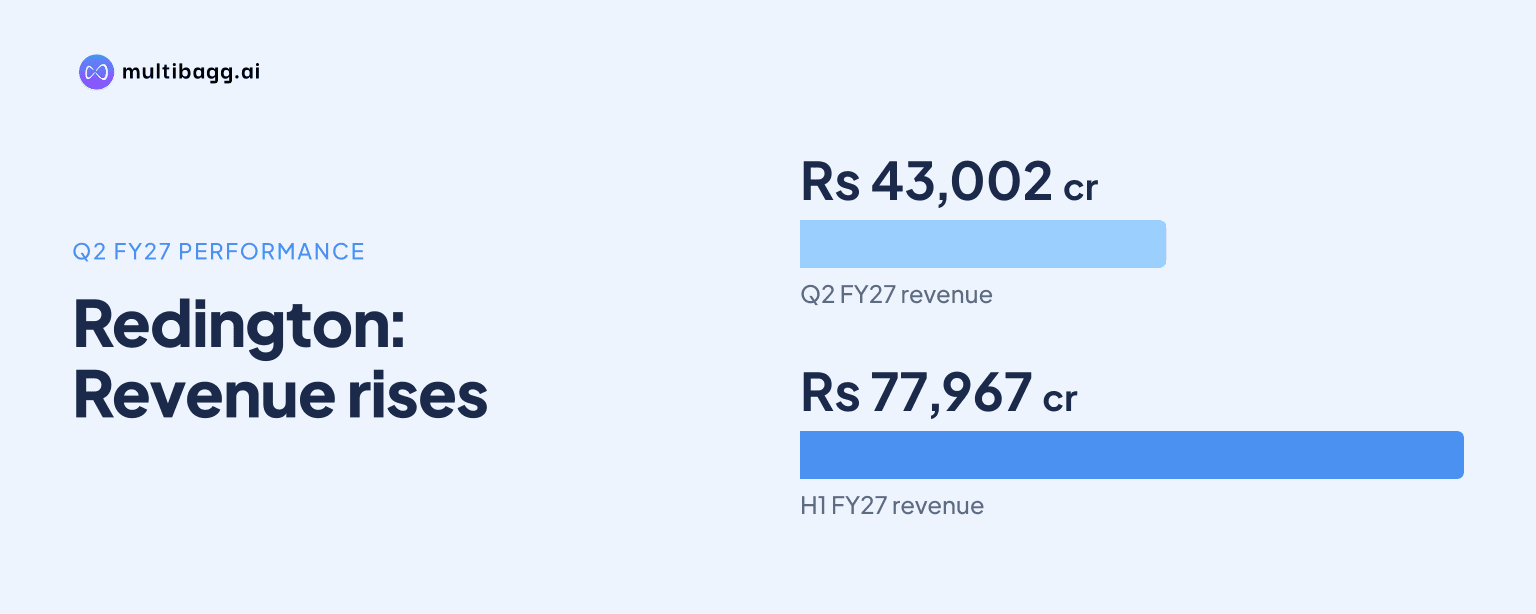
Redington Limited reported Q2 FY27 consolidated revenue of ₹43,002 crore, a 48% year-on-year increase, while profit after tax before exceptional items rose 50% to ₹581 crore. The result marked the company’s highest quarterly revenue and profit performance, supported by India’s 67% revenue growth and a 91% increase in Technology Solutions Group revenue.
Know Redington inside out
Results, valuation, peers and who's buying, in one view.
What did Redington report for Q2 FY27?
Redington reported consolidated revenue of ₹43,002 crore for Q2 FY27, compared with growth of 48% year on year. Profit after tax, excluding exceptional items, stood at ₹581 crore, up 50% from the corresponding quarter. The company described both measures as its strongest quarterly performance.
The reported figures include different profit measures disclosed across the results material. Revenue from operations was reported at ₹42,947 crore, up 47.7% year on year, while reported net profit was ₹422.5 crore, up 20.6%. Separately, the earnings-call summary stated that reported profit attributable to shareholders was ₹541.32 crore and profit after tax before the exceptional Arena impairment was ₹581 crore.
For the first half of FY27, consolidated revenue reached ₹77,967 crore, a 41% year-on-year increase. Profit after tax excluding exceptional items rose 61% to ₹1,067 crore. Redington said these were the highest revenue and profit figures it had recorded for a first half.
Which businesses drove Redington’s quarterly growth?
India was the largest disclosed growth driver, with revenue increasing 67% year on year during Q2 FY27. Redington attributed the performance to broad-based momentum across mobility, endpoint solutions and technology solutions in the Indian distribution business.
Technology Solutions Group, or TSG, recorded 91% year-on-year growth. Management identified TSG as the leading prospective growth driver, followed by Software Solutions Group, or SSG. It said investment in people, platforms and capabilities for SSG, TSG and artificial intelligence would continue, subject to the ability of each investment to generate durable returns.
Redington also stated that India, GCCL, covering the GCC countries and Levant, and Africa were expected to remain important growth markets. However, management noted that conditions in the UAE and Saudi Arabia could depend on geopolitical disruption. It also flagged a more cautious view for mobility, ESG and MSG.
How did costs and returns change in the quarter?
Redington said operating expenses grew 40% in Q2 FY27, below its 48% revenue growth rate. This gap indicated operating leverage during the period, with the company reporting that core-business growth translated into stronger earnings before the effect of exceptional items.
Return on equity improved to 21.6%, while net return on capital employed rose to 22.7%. Excluding Arena, Redington reported return on equity of 24.4% and net return on capital employed of 28%. These metrics reflect management’s separate presentation of results with and without the Arena business.
Arena remained the principal area requiring corrective action, according to the company. Redington did not provide a fresh timeline for that corrective action in the supplied results material. The distinction between reported profit and profit before exceptional items is therefore relevant when assessing the quarter’s earnings performance.
Got a follow-up? Ask IRIS
What challenges did Redington face during Q2 FY27?
Redington delivered the quarter against geopolitical disruption in West Asia, changing component prices and continued supply-chain complexity, according to Chief Executive Officer V.S. Hariharan. These conditions were cited alongside the strong revenue outcome, rather than as factors that prevented the company from expanding.
The exposure to West Asia makes developments in UAE and Saudi Arabia relevant to the company’s near-term operating environment. Management said India, GCCL and Africa should remain strong growth drivers, but specifically linked the outlook for UAE and Saudi Arabia to geopolitical disruption.
Component-price changes and supply-chain conditions can influence technology distribution operations because the business manages product flows across multiple markets and categories. Redington’s reported quarterly growth shows that demand and execution remained strong in Q2 FY27, although the company’s comments also indicate that external conditions remained uneven across regions.
What does the NeoCloud opportunity mean for Redington?
Redington estimated India’s NeoCloud data-centre opportunity at ₹150,000 crore over the next four years. Management linked that estimate to an expected expansion in Indian NeoCloud capacity from 1.5 GW to 7 GW and subsequently 12 GW.
The opportunity is relevant to TSG, which delivered 91% year-on-year growth in Q2 FY27 and was identified as Redington’s leading growth driver. The estimate is management’s assessment of the addressable opportunity, not a revenue forecast or order book disclosed by the company.
For investors, the quarter places the focus on whether TSG and India can sustain their contribution while Redington manages Arena and regional uncertainty. The company’s revenue growth, lower relative growth in operating expenses and improved return ratios provide the key operating markers disclosed for the period.
Conclusion
Redington’s Q2 FY27 results combined 48% consolidated revenue growth to ₹43,002 crore with a 50% increase in profit after tax before exceptional items to ₹581 crore. India and TSG were the clearest contributors, while operating expenses grew slower than revenue and return ratios improved. The reported profit measures also show why exceptional items and Arena remain important for a complete reading of earnings.
The next areas to watch are the progress of corrective action at Arena, demand across India, GCCL and Africa, and conditions in UAE and Saudi Arabia amid geopolitical disruption. Management has also identified a ₹150,000 crore NeoCloud opportunity over four years as India’s capacity expands from 1.5 GW to 7 GW and then 12 GW.