Actions
Action Type



Welcome to Multibagg AI
Log in to access personalized features
IRIS
Multibagg AI is an AI powered stock research and analysis platform. We provide data, information, content, and analytics for publicly traded Indian companies listed on NSE and BSE. AI can make mistakes, check important information.
Research powered by GOALZEN CAPITAL SERVICES PRIVATE LIMITED · SEBI Research Analyst INH000013448
Prices might be delayed by a few minutes.
Join our Exclusive Community


Join our Exclusive Community
Made with 💙 in India. © Finsky Technologies Pvt Ltd. 2026


Get instant AI-powered insights about company performance, financials, and strategy. Ask questions about trends, competition, and developments while receiving responses backed by official documents and market data, with clear attribution to source documents.

 Discovery themes featuring this stockDiscovery themes featuring this stock
| Symbol | Watchlist | Price | Market Cap | P/E | P/B | Div Yield (%) | ROE (%) | ROCE (%) | ROA (%) |
358.00 | 88,956 Cr | 17.15 | 1.50 | 0.56 | 7.97 | 5.82 | 5.83 | ||
22749.55 | 82,082 Cr | 51.63 | 3.44 | 0.66 | 6.64 | 8.92 | 4.87 | ||
4858.30 | 37,539 Cr | 39.58 | 5.33 | 0.41 | 14.10 | 13.35 | 5.07 | ||
1595.05 | 29,918 Cr | 31.36 | 1.66 | 0.57 | 6.34 | 7.54 | 2.86 | ||
1158.55 | 21,756 Cr | 11.40 | 1.06 | 0.65 | 10.40 | 10.75 | 6.93 | ||
739.15 | 17,466 Cr | 27.35 | 2.16 | 0.34 | 3.20 | 6.16 | 3.84 | ||
116.95 | 15,945 Cr | 22.11 | 2.43 | 4.21 | 11.15 | 9.99 | 4.96 | ||
| Median: 7 Co. | — | 1158.55 | 29,918 Cr | 27.35 | 2.16 | 0.57 | 7.97 | 8.92 | 4.96 |
Bearish
4
Neutral
7
Bullish
3
Bearish
27
Neutral
7
Bullish
12
Bearish
23
Neutral
0
Bullish
9
Bearish
4
Neutral
7
Bullish
3
Bearish
4
Neutral
7
Bullish
3
Bearish
23
Neutral
0
Bullish
9
Bearish
23
Neutral
0
Bullish
9
Bearish
23
Neutral
0
Bullish
9
Ambuja Cements Limited is an integrated Indian cement manufacturer and part of the Adani Group, selling cement primarily under the Ambuja brand and operating an expanded platform of roughly 109 MTPA capacity after recent acquisitions and amalgamations, with nationwide grinding, clinker and captive logistics assets that support both trade and institutional segments.
Q1 FY27 performance showed revenue of ~INR9,500 crore, operating EBITDA of ~INR1,589 crore (16.7% margin) and PAT of INR660 crore, with reported net cost reduced sequentially to INR4,241 per metric ton; management attributes cost gains to clinker factor improvement, higher blended cement share and renewable/WHRS ramp‑up while volumes were selectively moderated to prioritise value over low‑margin non‑trade sales.
The company is executing four strategic priorities: profitable growth through premiumisation and trade focus, structural cost leadership via logistics/RE/AFR/WHRS initiatives, disciplined capital allocation with major organic expansions to 119 MTPA by FY27, and building a future‑ready enterprise where sustainability and technology are drivers of efficiency and shareholder value.
Ambuja has a large renewable energy programme (reported RE capacity ~973 MW and WHRS 228 MW), has begun monetising surplus power and fly ash sales, and has committed to a 60% green power consumption target by FY28; captive power plus coal block development and AFR adoption underpin management’s pathway to reduce overall unit costs materially.
Management targets ~8% volume growth for FY27, INR4,250 per ton full‑year cost target, incremental cost savings of ~INR130–150 per ton from multiple initiatives, and FY27 capex around INR6,500 crore focused on both growth and efficiency, indicating continued aggressive capacity and capability investment while prioritising returns.
Cement & Cement Products
Cement & Cement Products
88,956 Cr
High Risk
17.2
30.2
1.6
1.5
588.55
341.30
Sales CAGR
Profit CAGR
ROE
ROCE
Upcoming Result Date: Oct 28, 2026
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone

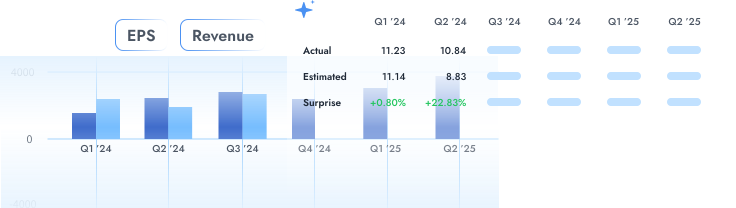



Ambuja Cements Ltd (AMBUJACEM) is currently trading at 358.00 per share. Stock prices fluctuate during market hours on NSE and BSE based on demand, company updates, and overall market conditions. Refer to the live price chart above for the most recent price movement.
Ambuja Cements Limited is an integrated Indian cement manufacturer and part of the Adani Group, selling cement primarily under the Ambuja brand and operating an expanded platform of roughly 109 MTPA capacity after recent acquisitions and amalgamations, with nationwide grinding, clinker and captive logistics assets that support both trade and institutional segments. Q1 FY27 performance showed revenue of ~INR9,500 crore, operating EBITDA of ~INR1,589 crore (16.7% margin) and PAT of INR660 crore, with reported net cost reduced sequentially to INR4,241 per metric ton; management attributes cost gains to clinker factor improvement, higher blended cement share and renewable/WHRS ramp‑up while volumes were selectively moderated to prioritise value over low‑margin non‑trade sales. The company is executing four strategic priorities: profitable growth through premiumisation and trade focus, structural cost leadership via logistics/RE/AFR/WHRS initiatives, disciplined capital allocation with major organic expansions to 119 MTPA by FY27, and building a future‑ready enterprise where sustainability and technology are drivers of efficiency and shareholder value. Ambuja has a large renewable energy programme (reported RE capacity ~973 MW and WHRS 228 MW), has begun monetising surplus power and fly ash sales, and has committed to a 60% green power consumption target by FY28; captive power plus coal block development and AFR adoption underpin management’s pathway to reduce overall unit costs materially. Management targets ~8% volume growth for FY27, INR4,250 per ton full‑year cost target, incremental cost savings of ~INR130–150 per ton from multiple initiatives, and FY27 capex around INR6,500 crore focused on both growth and efficiency, indicating continued aggressive capacity and capability investment while prioritising returns.
Over the past 52 weeks, Ambuja Cements Ltd has traded between a low of ₹341.30 and a high of ₹588.55. The 52-week high and low indicate the stock’s price range over the last year and help investors understand its volatility and recent trading levels.
Ambuja Cements Ltd has a market capitalization of approximately 88,956.46. Market capitalization represents the total value of a company’s outstanding shares and helps investors understand its size, stability, and relative risk compared to other listed companies.
Ambuja Cements Ltd’s investment profile depends on its business fundamentals, valuation, and long-term outlook. The stock currently trades at a PE ratio of 17.15 and operates in the its sector sector. Investors typically assess financial performance, growth prospects, and individual risk tolerance before making investment decisions.
Based on its market capitalization of 88,956.46 Cr, Ambuja Cements Ltd is classified as a Mid Cap stock. Large-cap stocks are generally more stable, while mid-cap and small-cap stocks tend to offer higher growth potential along with higher price volatility.
Ambuja Cements Ltd operates in the its sector sector. Sector classification matters because companies in the same sector are often affected by similar economic conditions, regulatory changes, and competitive dynamics, which can influence overall stock performance.
The Price-to-Earnings (PE) ratio of Ambuja Cements Ltd is 17.15. The PE ratio compares a company’s share price to its earnings and is commonly used to assess valuation. Comparing the PE ratio with sector peers and historical levels provides better context.
They approved a Special Resolution for the Scheme of Amalgamation of ACC Limited with Ambuja Cements at an NCLT-convened equity shareholder meeting.
Ambuja Cements disclosed that it will interact with investors and analysts on November 18 and 19, 2026 at the Adani Annual Conference 2026 in Singapore.
They approved a Special Resolution for the Scheme of Amalgamation of ACC Limited with Ambuja Cements Limited at an NCLT-convened meeting.
Ambuja Cements’ board has approved schemes to merge ACC Limited and Orient Cement Limited into Ambuja, creating a single consolidated “One Cement Platform”, subject to approvals.